
By Ima Niboro
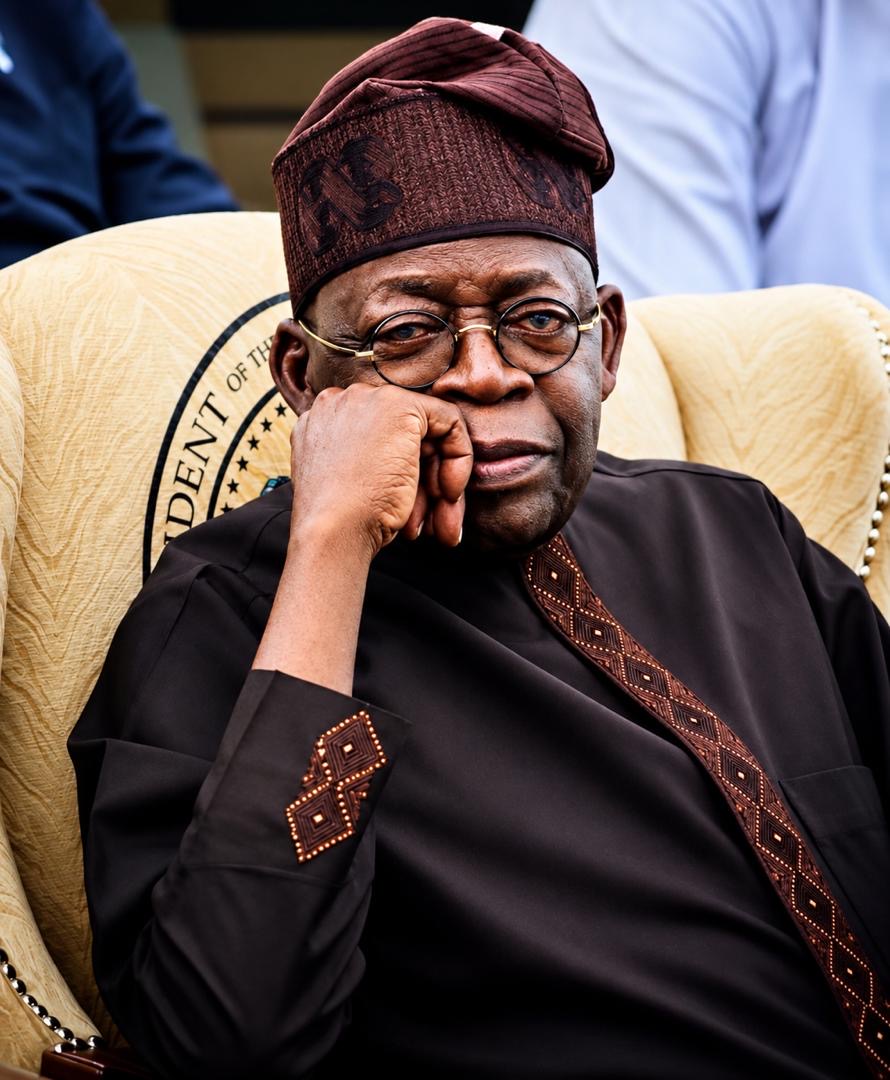
Today, President Bola Ahmed Tinubu formally inaugurated the All Progressives Congress Presidential Campaign Council. With that ceremony, the work of presenting the case for his re-election to Nigerians begins in earnest.
For those of us in the Media and Strategic Communications Directorate, however, the work did not begin today. We have been at it since August, putting together the structures, strategy, and communications architecture required for what will undoubtedly be an intense national campaign. Today was the formal inauguration by Mr President and the signal for the machinery to move into full campaign mode.
Within the APC PCC Media and Strategic Communications Directorate are six subcommittees. I have the privilege of serving on three of them: the Committee of Campaign Spokespersons, the Strategy Committee, and the Committee on the Screening of Media and Advertising Agencies that will work with the Presidential Campaign Council.
These are responsibilities I have taken on with a clear understanding of what lies ahead.
I have always been unequivocal about my support for the Tinubu administration. That support does not mean I delude myself that everything is perfect. Far from it—
because tough but completely unavoidable decisions have been made that have had real and sometimes difficult consequences for many Nigerians.
Indeed, I have always made the point that, in terms of sheer numbers, we members (and supporters) of APC are at the top demographic of those living through these economic realities. Our NIN-verified membership stands at about 12.8 million. (PDP – 2.4 million, ADC – 1.6 million, NDC – 700,000). Our members and supporters are traders, civil servants, farmers, transporters, professionals, artisans, and businesspeople. We buy from the same markets, pay the same transport fares, and confront the same economic pressures as everybody else. But despite these, we remain focused and confident, because joy comes in the morning—and that morning is here!
So, this campaign cannot be built on denying the obvious. It must be built on explaining why difficult decisions were taken, what they have achieved, where they are taking the country, and, most importantly, when and how those gains translate into better lives for ordinary Nigerians.
This is the central conversation of this campaign; and it is called—From Reform to Prosperity!
When President Tinubu assumed office in 2023, Nigeria faced deep fiscal and monetary distortions that had accumulated over several years. Central Bank financing of government deficits through Ways and Means advances (meaning printing cash, Zimbabwe Style, backed by nothing) had risen to about N30 trillion.
The foreign-exchange system had become fragmented across multiple windows. By May 2023, the official NAFEX rate was about ₦465 to the dollar, while the parallel-market rate was about ₦763 — a differential of roughly 63 per cent. That enormous gulf created opportunities for arbitrage and rent-seeking, while businesses without privileged access to official foreign exchange were forced into a much more expensive, arbitrary, and unsustainable parallel market.
This President could have continued the pillage and made humongous gains for himself and his allies, like was going on before he took power. But he said no. Nigeria first! This country must respect that.
Then there was the petrol subsidy regime, which consumed enormous public resources while encouraging distortions, arbitrage, and heavy smuggling. Government revenues were under severe pressure, debt-service obligations were at almost 98 per cent of the budget, investors were voting with their feet due to economic uncertainty, and the country faced what the World Bank described as the danger of a “fiscal cliff.”
Obviously, something had to give. The country was collapsing under the weight of its own contradictions, and the choice before Tinubu was clear: Continue the arbitrariness, reinforce the slide, and supervise Nigeria’s final collapse, or execute a course correction, block the leakages, stop the haemorrhage, and return the country to a path of sustainable growth and economic stability.
Because he chose the latter, history will be kind to him!
So, petrol subsidy was removed. Multiple foreign-exchange windows were unified, and the exchange rate moved towards a market-determined system. The Central Bank tightened monetary policy, began rebuilding reserves, addressed outstanding foreign-exchange obligations, and stopped merely printing money (who still does that in the 21st century!) to finance fiscal deficits.
His administration simultaneously embarked on tax, oil and gas, power, infrastructure, and credit reforms intended to rebuild the foundations of the economy.
The first phase was painful, no doubt. Fuel prices rose. The naira underwent a severe adjustment. Inflation impacted household incomes. Interest rates increased as the monetary authorities fought inflation. Businesses and families carried a heavy burden.
But three years later, the evidence increasingly shows that Nigeria has moved beyond the most difficult stage of that adjustment. The numbers are now telling a different story.
Foreign reserves have climbed above $54 billion, compared with about $32 billion in mid-April 2024. Nigeria’s external position has strengthened considerably. The World Bank says real GDP grew by 4.2 per cent in the first half of 2026, compared with 3.9 per cent in the corresponding period of 2025 and 3.5 per cent in 2024.
The same World Bank report says that stronger growth stabilised Nigeria’s poverty rate for the first time since 2019. That does not mean poverty has disappeared, but it represents an important change in direction that leads to a bright new future for our great country.
Hand in hand, Nigeria’s current-account position has also strengthened, as rising reserves provide a bigger buffer against external shocks. You remember when foreign airlines were leaving Nigeria in droves because they had a room full of naira and no dollars to convert it to? Or when you couldn’t use your naira card for any international transactions, whether locally or abroad?
Those days are gone!
And the international financial community is noticing.
In May, S&P Global Ratings raised Nigeria’s long-term sovereign credit rating from B- to B, citing an improving macroeconomic profile, stronger oil production, increased domestic refining capacity, and the liberalisation of the foreign-exchange regime.
In August, Moody’s revised Nigeria’s outlook to Positive from Stable while retaining its B3 rating, citing stronger external resilience, higher foreign-exchange reserves, and economic growth.
Then, last week, Fitch revised Nigeria’s sovereign outlook from Stable to Positive while affirming its B rating. Among the factors Fitch identified were stronger external buffers, greater exchange-rate flexibility, disinflation, and increased confidence in the continuity of the reform framework.
J.P. Morgan has now included Nigeria among the countries in its new GBI-EM Edge frontier local-currency bond index, another avenue through which global investors can assess exposure to Nigeria’s domestic debt market. And its banking arm, JP Morgan Chase, is bringing a brand new investment bank to Nigeria.
Clearly, the world knows that Nigeria has not solved all its problems. Neither should we, back home here, pretend that credit ratings put food on anybody’s table.
But what these developments state unequivocally is that institutions whose business it is to assess sovereign risk increasingly see powerful changes in Nigeria’s economic fundamentals. And lower sovereign risk, if sustained, means lower costs, greater investment, more businesses, more jobs, greater resources to develop our country, and ultimately money in the pocket and food on the table.
The next phase is therefore the most important one: converting economic stabilisation into prosperity.
That means bringing inflation down further so that wages recover more and more purchasing power. It means maintaining foreign-exchange stability so businesses can plan and price their products with greater certainty. It means increasing food production and attacking the structural problems driving up food prices.
It also means ensuring that higher Federation revenues continue to translate into better roads, hospitals, schools, water, security, and social services at federal, state, and local government levels.
It means expanding conditional cash transfers to the poorest of the poor among us, it means increasing consumer and business credit so that Nigerians can finance homes, vehicles, education, and enterprises without having to possess the entire purchase price in cash.
It means deepening the CNG programme and electric-powered transport interventions to reduce the cost of mobility. It also means expanding domestic refining so that Nigeria can put a final stop to importing petroleum products and the foreign-exchange pressures associated with that.
Moving from Reform to Prosperity means attracting the investment required to create millions of productive jobs. But above all, it means making sure that the macroeconomic recovery moves from the computer screens, the big and sometimes confusing numbers on the spreadsheets, rating reports, and government statistics into Nigerian pockets, kitchens, and dining tables.
That, in my view, is the great assignment of the next phase, and there’s no one better positioned to accomplish this task than the chief visioner of the reform programme, President Bola Ahmed Tinubu himself.
Our national economic foundations have been reset. Now the Nigerian people are about to see and feel the full benefits of the house built upon these structures.
So much has been done already. At the heart of the Tinubu administration’s interventions have been programmes designed to put money in people’s pockets, ease the cost of living, and widen access to opportunity. The national minimum wage has been increased, while conditional cash transfers are providing support to vulnerable households. Students who might otherwise be unable to afford higher education are benefiting from the Student Loan Scheme through NELFUND, while consumer credit, YouthCred, the Nigeria Youth Investment Fund, and loans and grants for MSMEs are expanding access to finance for workers, young people, entrepreneurs, and small businesses.
The administration has also targeted the everyday pressures Nigerians feel most directly—food, healthcare, transportation, and jobs. Agricultural programmes, including dry-season farming support, tractor deployment, and the National Agricultural Growth Scheme, are increasing food production and strengthening farmers. Primary healthcare revitalisation and expanded cancer-treatment infrastructure are improving access to essential healthcare, while the CNG initiative is providing a cheaper transportation alternative. Programmes such as 3MTT, digital youth training, and the Creative Economy Development Fund are equipping young Nigerians with skills and opening new pathways to employment and enterprise.
Beyond these immediate interventions, major investments are being made in security, electricity, roads, rail, ports, and other infrastructure that affect daily life and economic opportunity. Counterterrorism operations are daily strengthening security, while power-sector reforms, grid expansion, the Zungeru hydropower project, national road rehabilitation, the Lagos-Calabar Coastal Highway, Sokoto-Badagry Highway, and revitalised Abuja Metro are improving the foundations for growth. The broader reforms in taxation, foreign exchange, public revenue, debt management, and the petroleum sector are all parts of the machinery required to sustainably finance a more secure country, improve decrepit public services, create more jobs, and improve living standards for our people.
This is why the work to reelect this President shifts into high gear effective today.
The coming elections should provide Nigerians with the opportunity to examine records, policy choices, consequences, and alternatives. And President Tinubu will have to defend his record before Nigerians, as every incumbent seeking re-election should. His challengers will equally have to explain not only what they would do differently, but how they would do it, what it would cost, and what consequences would follow.
For those of us entrusted with communicating the President’s case, our responsibility is therefore substantial.
We will explain without insulting the intelligence of Nigerians; defend without denying obvious difficulties; persuade with facts. We will celebrate the successes and acknowledge where more work remains to be done. And we will demonstrate why continuity of the reforms offers the country a path towards stronger and more broadly shared prosperity.
I have seen before what happens when an incumbent government is unable to persuade Nigerians that its work deserves to continue.
I served President Goodluck Ebele Jonathan and watched his administration lose re-election in 2015. That experience taught me a permanent lesson about politics: performance alone is never enough. A government must continuously explain what it is doing, why it is doing it, and where it intends to take the country.
That lesson remains branded on my mind, and I carry its weight with me always.
In this election, we will make the case vigorously, respectfully, and factually. Nigerians will ultimately make their choice, as is their democratic right. For us, however, there can be no complacency.
The campaign has begun. The work begins in earnest.
And we shall win!
Discover more from Keeping Them Honest
Subscribe to get the latest posts sent to your email.